The Short Answer
Yes. Homes in Ruidoso, Alto, Capitan, and Cloudcroft are still being written today. But the answer depends on which door you walk through, and most people do not know there are three.
The first door is the standard market: the carriers whose names you recognize. A few are still writing in Lincoln County, and they are selective. The second door is the surplus-lines market: specialty carriers that exist to write property the standard market will not touch, at a higher premium and with different terms. The third door is the New Mexico FAIR Plan, the state’s insurer of last resort. Our job is to get you through the first door if we can, the second if we must, and to explain exactly what you are giving up if it comes to the third.
Why It Got This Hard
The carriers are not guessing about our risk. FEMA’s National Risk Index rates Lincoln County’s wildfire risk “Relatively High,” in the 98.76th percentile nationally, with an expected annual wildfire loss of $14,534,902.53. Every underwriter with a login can pull that number.
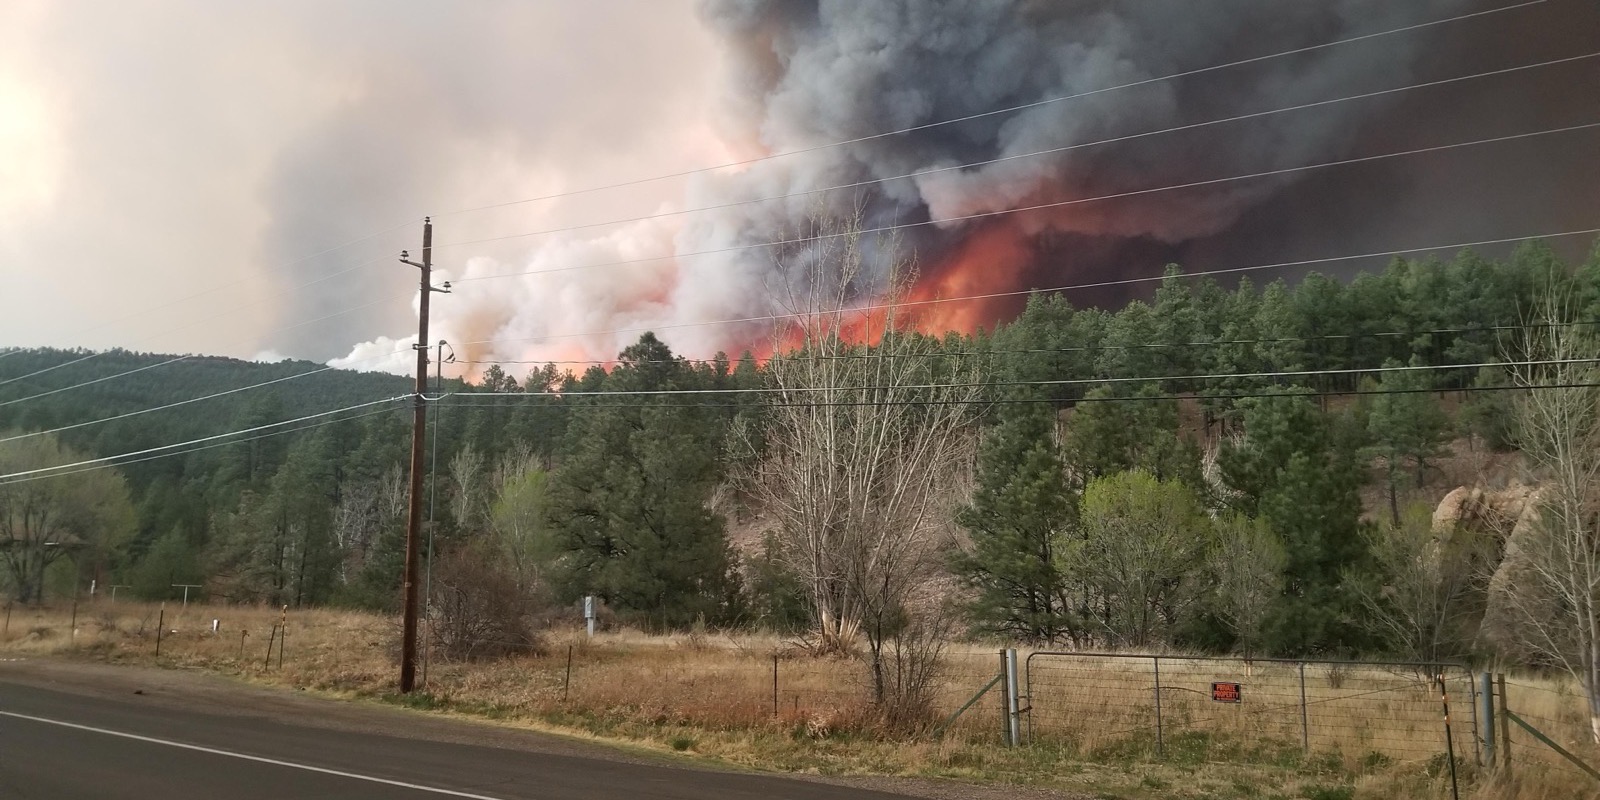
Then 2024 happened. FEMA’s preliminary damage assessment for the South Fork and Salt Fires counted 744 residences destroyed. Only 44.0% of the affected residences were insured. The rest were rebuilding on savings, on federal assistance, or not at all. Carriers looked at that loss and at the burn-scar flooding that followed, and many of them left.
They were already leaving. Between January 1, 2021 and July 1, 2024, the New Mexico Office of Superintendent of Insurance counted over 10,000 homeowners non-renewals statewide. If you have received one, you are in a very large club.
What the Underwriters Are Scoring
Every carrier still writing here is reading the same handful of things. Most of them are looking at a satellite image of your lot before they ever look at your application.
Defensible space. The first thirty feet around the house is what the underwriter cares about most. Ladder fuels, brush against the siding, a woodpile on the deck, trees touching the roof. If it burned in 2024, they want to see that the lot has been cleared since.
Roof. A Class A roof (metal, tile, asphalt composition) is close to a requirement now. A wood shake roof is close to a decline. Age matters too, and a roof older than fifteen or twenty years is a question on its own.
Vents and openings. Ember intrusion is how most homes actually burn. Ember-resistant vents, screened eaves, and enclosed decks are cheap upgrades that show up in the score.
Distance. How far to the nearest fire station and the nearest hydrant, and whether the road in is paved and wide enough for an engine.
Loss history. A prior claim on the property is not automatically a decline, but it has to be explained.
How to Give Them a File They Can Say Yes To
The difference between a decline and a quote is usually the file. Here is what we ask for, and why.
- Photos of all four sides of the house and the lot, taken after your clearing work. Underwriters trust a photo more than a checkbox.
- Receipts and dates for the roof, the vents, the tree work. A receipt turns “we cleared it” into a fact.
- A short mitigation write-up. Half a page: what you did, when, and what is scheduled. We will draft it with you.
- Your current declarations page and the non-renewal letter, if you have one. The letter usually tells us the reason, and the reason tells us which carriers to skip.
We have brought Verisk and IBHS to Ruidoso to see mitigation work in person, and we hold defensible-space seminars so homeowners can learn what those groups are scoring. None of this is a secret. It is just work, and it is work that moves your file from one pile to the other.
What It Costs
We will not pretend the standard market price of 2019 is coming back. What we will do is shop every carrier still writing here, show you the options side by side, and be honest about which door you are in. A surplus-lines policy on a well-mitigated mountain home is real coverage. The FAIR Plan is real coverage with real limits. Either one is a long way from the 56% who had nothing.
If you own a home in the Sacramento Mountains and you have not had it shopped since the fires, send us what you have. We will tell you where it stands.