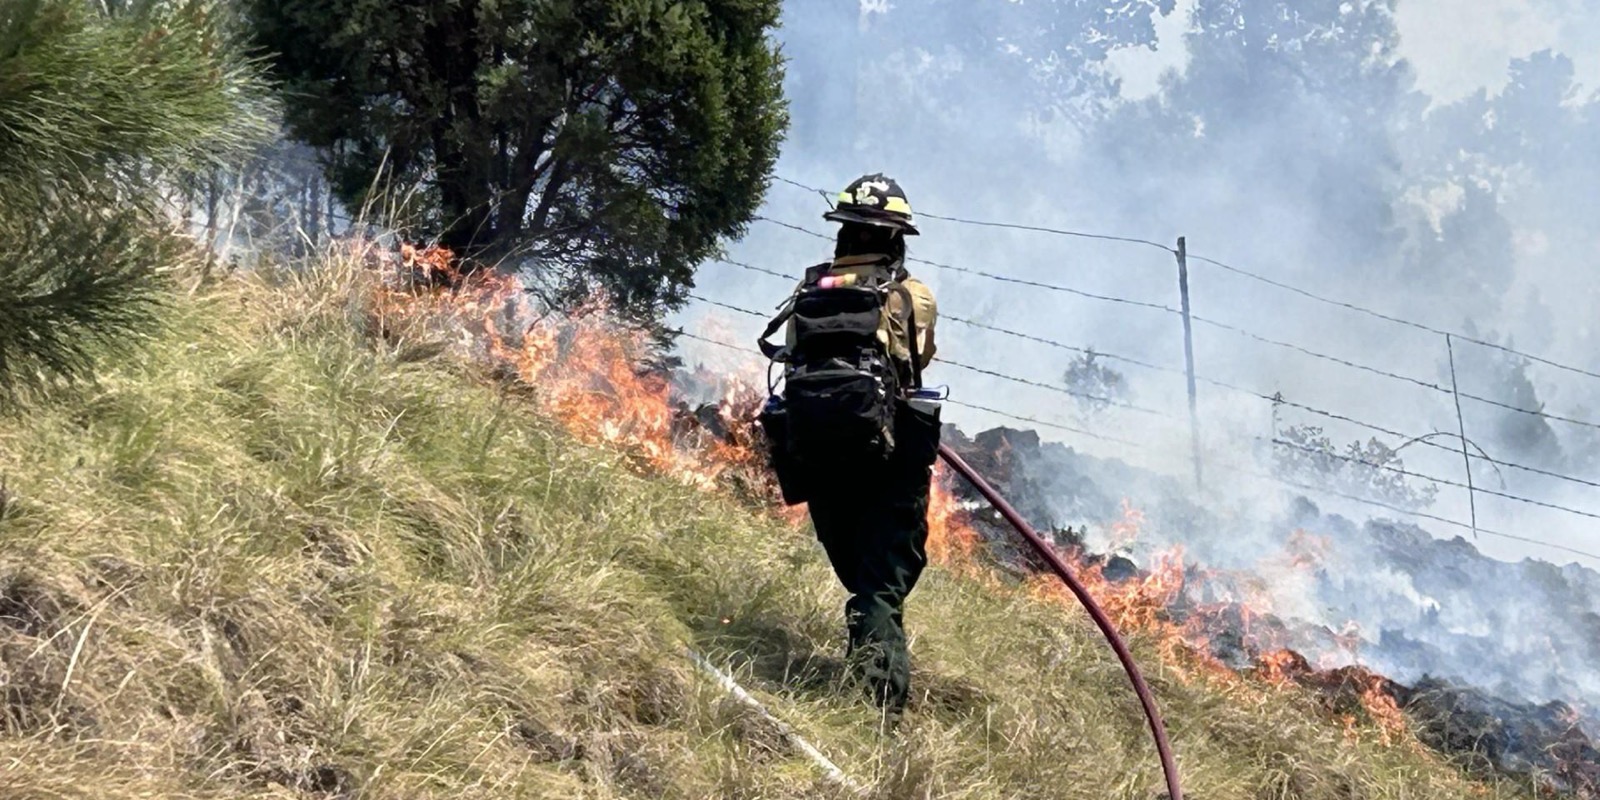
A mountain-home quote asks so many questions because, in our part of New Mexico, each answer decides which kind of insurance market will look at the house at all. In a city, a home quote can run on an address and a square-footage figure. In Ruidoso, Alto or Cloudcroft, the underwriter needs to know how the house would stand up to embers, whether a fire engine can reach it, and how quickly someone would notice a problem. Every question on the form is one of those three in disguise.
What are they really asking about the house?
The longest stretch of a mountain application is about how the house is built. The questions that matter most for wildfire are usually these:
- The roof. Material, age, and fire rating. A Class A rated roof, the highest rating for fire resistance, is one of the first details underwriters ask about.
- Vents and eaves. Embers get into homes through attic and foundation vents and open eaves. Fine metal mesh or ember-resistant vents are a common follow-up question.
- Siding and decks. Wood siding and a wood deck attached to the house read differently from stucco, stone or fiber cement.
- The first five feet. What sits right against the walls: pine needles, a woodpile, juniper shrubs, a gravel border.
Why does the driveway matter?
Questions about the road in, the slope of the lot, and whether there is a turnaround are about access for fire crews. A long, narrow, one-way driveway under heavy ponderosa canopy is a different risk from a paved street with two ways out.
Distance to the nearest fire hydrant and to a staffed fire station feeds what is called the public protection class, a rating that most of the property market uses. Two houses that look alike can rate very differently because one is three blocks from a hydrant and the other is a mile up a forest road.
Why the questions about occupancy and the people in the house?
Who lives there and how often shapes which policy form fits. A full-time residence, a second home, and a cabin rented to guests each typically call for a different kind of policy. About 43 percent of Ruidoso’s housing units are seasonal homes, so these questions come up on most of the files we see. We covered why in our post on seasonal homes.
Questions about prior claims, past non-renewals and how long the house has been insured are about history. A non-renewal is common here, and leaving it off the application can cause a problem later. If you have one, our post on what happens after a non-renewal walks through it.
Does the answer change which market writes the house?
Often, yes. The standard market, sometimes called admitted carriers, tends to have the narrowest appetite for wildfire exposure. The excess and surplus lines market writes many homes the standard market will not, usually on different terms. The New Mexico FAIR Plan is the insurer of last resort. The answers on the application are how a house gets sorted among the three.
That is the honest reason we ask for photos of the roof, the vents and the yard. A picture of fresh defensible-space work often does more for a file than a sentence describing it.
How to make the process go faster
Have these ready before the call: your current declarations page, the roof’s age and material, any receipts for mitigation work, and a few photos of each side of the house and the yard. If you have a defensible-space assessment from the fire department or the state forestry division, bring that too.
If you own a home in the Sacramento Mountains and want a quote that is built on the right answers the first time, see our home and property coverage, then start a quote or call our Ruidoso office at (575) 434-2719. We will go through the questions with you instead of handing you a form.
This article is general information about how coverage typically works, not advice about your specific situation. Every policy reads a little differently, and yours is the only thing that says what you have. If you’d like someone to read it with you, call our Sudderth Drive office — that’s what we’re here for.